OpenAI introduced ChatGPT Wallet on November 13 as a way for an AI agent to complete purchases with the user's approval. The announcement names American Express, Mastercard and Visa as partners. Initial availability is through dots for adult ChatGPT Pro subscribers in the United States. The materials reviewed do not announce availability in Bulgaria.
Separating selection from payment
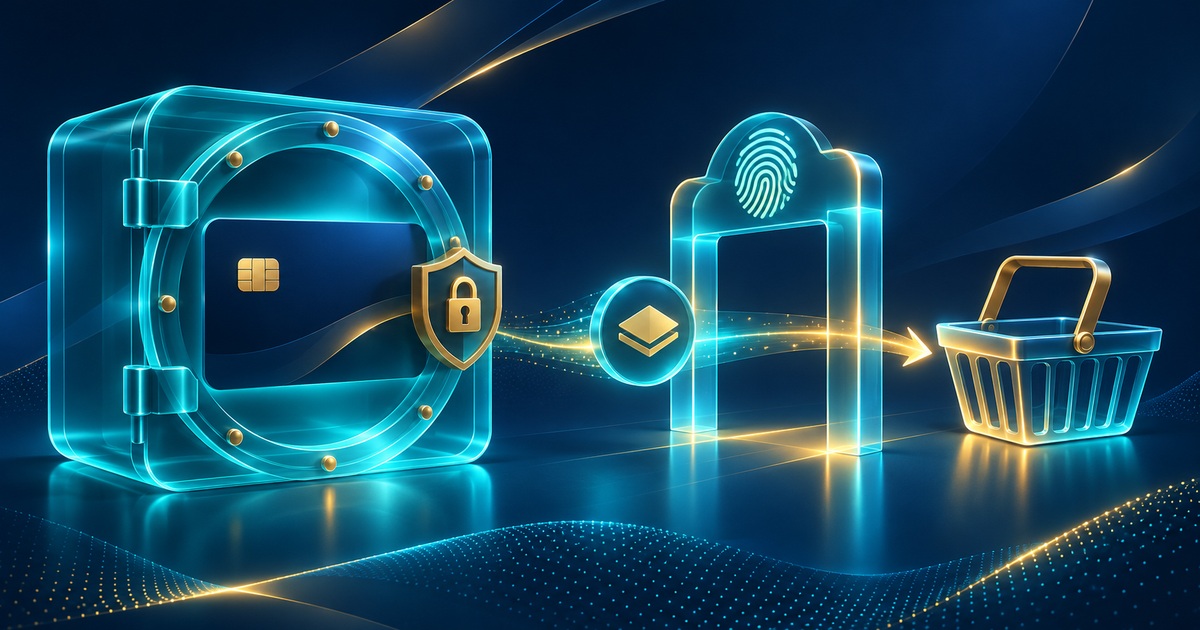
In the launch workflow, a person reviews the purchase and authorizes it through a security check, such as biometric confirmation. The payment network then supplies a substitute credential for checkout rather than exposing the actual card details. Broader delegation with pre-established limits is described as a future direction, rather than unrestricted spending available to everyone at launch.
That separation defines the significance of the news. Finding a suitable product does not itself authorize an agent to pay. An approved payment request is also different from an order accepted by the merchant. The help documentation explicitly distinguishes these states and advises checking merchant confirmation after an unclear outcome before trying again.
Who can use it?
The help center describes a gradual rollout to eligible US Pro accounts with a US billing address and an eligible US-issued card. A supported device is required for biometric purchase approval. Wallet operates in conversations with a dot, rather than ordinary Chat, Work or standalone Codex threads. Even an otherwise eligible user may not yet have access while the rollout continues.
A card stored for Wallet is separate from the payment method used for the ChatGPT subscription. Paying for an existing subscription therefore does not automatically establish that its card is ready for agent purchases. These are meaningful product boundaries for readers assessing what is actually available now.
What the surrounding systems receive
The privacy notice explains that a payment provider handles the secure card form, while OpenAI receives a tokenized credential and limited card information rather than the complete number and security code. The service also processes order, delivery, approval and fraud-prevention information. Hiding the underlying card from the agent does not mean that a transaction involves no exchange of personal or purchase data.
For merchants, official developer guidance describes compatibility with existing checkout pages without a mandatory Wallet-specific integration. Fraud systems can nevertheless reject legitimate agent-driven requests. The business remains responsible for the order, fulfillment and support. Authorization for one purchase does not permit reuse of its payment credential for a separate transaction.
Our editorial interpretation
For an online store, the more useful question is whether the path from accurate product information to a confirmed order remains traceable. Price, availability and delivery need to match what the person approved. If approval is followed by an unclear result, retrying without checking creates a duplication risk. That is a property of the entire transaction workflow, rather than just the language model.
The distinction also affects measurement. A successful product recommendation, a successful approval and a fulfilled order are three different outcomes. Counting the first as proof of the last would exaggerate the maturity of an agent-commerce deployment. A meaningful pilot should keep those stages separate in its reporting.
Wallet represents a concrete step toward agent-assisted commerce with specified regional and technical limits. The vendor publication establishes the announcement and described mechanism, rather than flawless performance at every shop. SIExpo did not make a purchase or test a payment card for this article.
The cover is an AI-generated editorial illustration, not a documentary photograph.